- Home
- Reports Store
- Medical Devices
Pacemakers Market
Customise your request
Need this report to answer something it does not cover? Tell us the decision you are facing and we will scope the work — or point you to a study that already answers it.
info@cortexmeridian.com+971 56 483 5090Report Scope
| Report ID / SKU | CM-MD-0006 |
|---|---|
| Report Code | CM-MD-P1-1006 |
| Report Type | Market Analysis & Forecast |
| Base Year | 2025 |
| Historical Period | 2021–2025 |
| Forecast Period | 2026–2035 |
| Geographic Scope | Global |
| Global Coverage | Yes |
| Regions Covered | North America; Europe; Asia-Pacific; Latin America; Middle East & Africa |
| Countries Covered | US; Canada; Mexico; UK; Germany; France; Italy; Spain; Netherlands; Switzerland; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; UAE; South Africa (20 countries) |
| Market Size Unit | USD Billion |
| Volume Unit | Implants / Units / Replacements |
| Report Format | PPT / WORD / EXCEL / PDF |
| Page Count | 180-220 |
| Delivery Timeline | 48 hours |
| Sample Available | Yes |
| Author / Analyst | Cortex Meridian Medical Devices Analyst Team |
| Publish Date | October 2026 |
| Last Updated | 2026-10-06 |
Market Overview & Definition
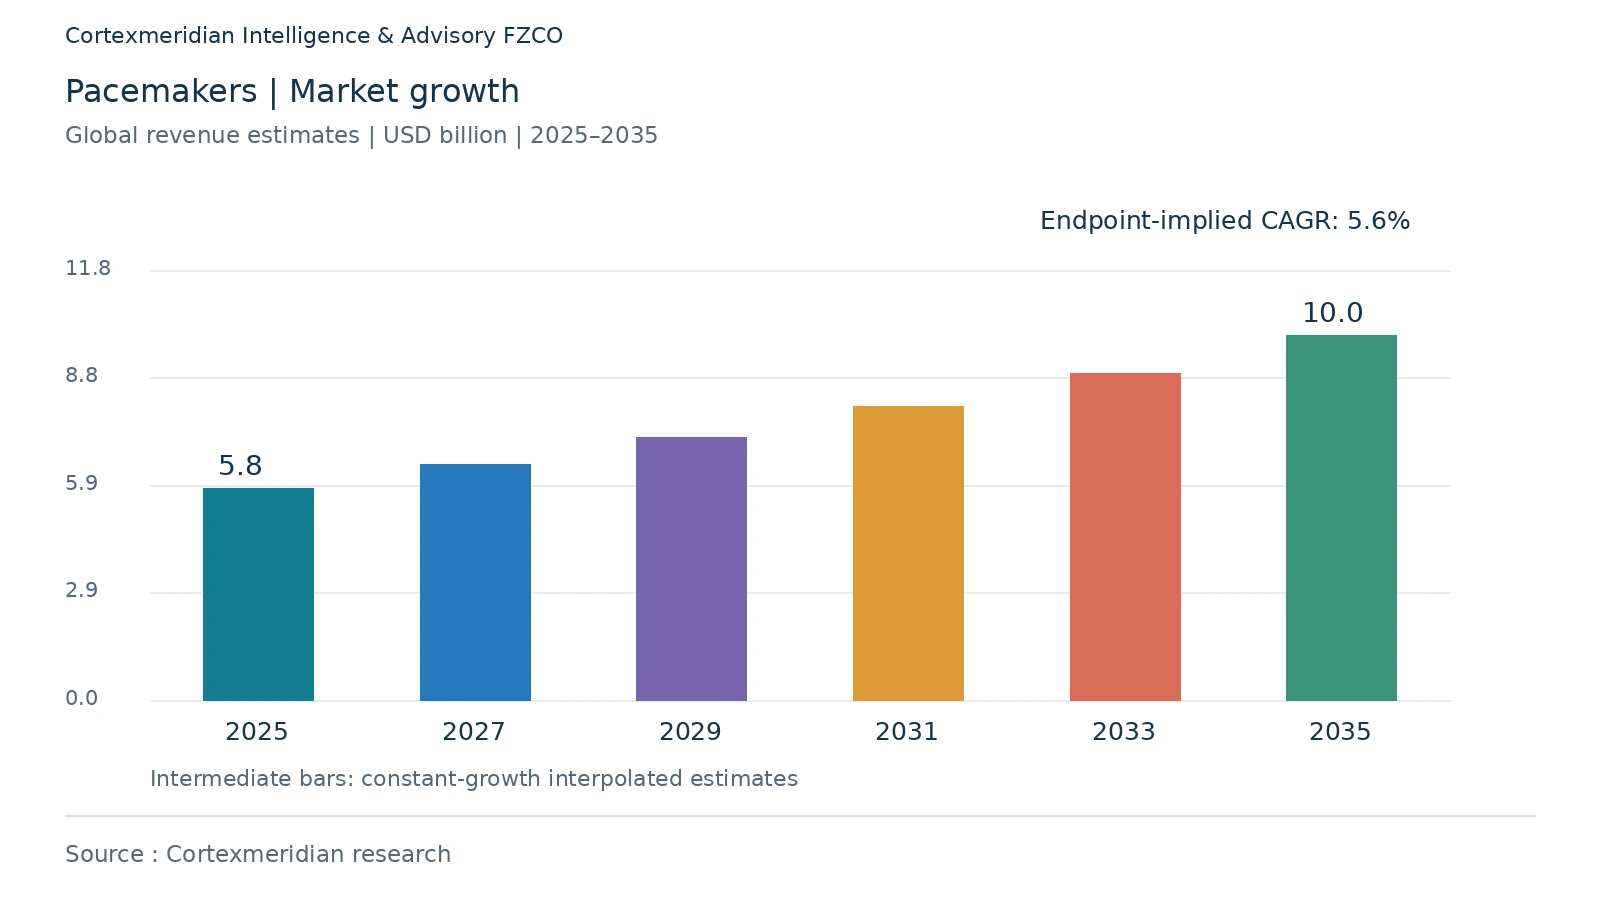
The global Pacemakers market is estimated at approximately USD 5.8 billion in 2025 and is projected to reach about USD 10.0 billion by 2035, implying a CAGR of 5.7%. The market is mature in conventional pacing, so the main source of growth is not a dramatic increase in implantation volume but a change in technology mix. Leadless pacemakers command premium pricing and address longstanding clinical concerns associated with transvenous leads and surgical pockets.
This technology shift is particularly important because a significant portion of the pacemaker market is replacement-driven. In a mature replacement market, vendors need either higher ASPs, broader indications or better clinical economics to accelerate revenue. Leadless systems offer all three. Abbott’s AVEIR DR expands leadless pacing into dual-chamber therapy, meaning the addressable patient pool is much larger than for earlier single-chamber systems. Medtronic’s Micra remains the principal competitive reference point.
The market’s growth therefore depends on physician confidence, long-term clinical evidence and reimbursement support for leadless pacing. As adoption moves from selected patients into broader use, product mix rather than raw implant volume is likely to be the dominant driver of market value.
Report Description
The Pacemakers Market covers revenue generated from the defined medical-device products, related consumables and software/services where directly attached to the device workflow. The report excludes unrelated pharmaceuticals and stand-alone healthcare services. The scope is designed for manufacturers, suppliers, distributors, hospitals, diagnostic providers, investors and strategy teams evaluating demand, technology shifts, pricing and competitive opportunity.
Overall Market Dynamics
Drivers
Aging population, arrhythmia prevalence, rising implant volumes, longer device life and improved leadless technology.
Restraints / Risks
Device recalls, infection and lead complications, reimbursement variation and mature-market replacement dependence.
Opportunities
Leadless pacemakers, MRI-compatible systems, remote follow-up, battery-life innovation and emerging-market penetration.
Strategic themes
AI/connectivity, workflow efficiency, reimbursement, regulatory approvals, recurring consumables/service revenue, and regional access expansion.
Segmentation & Scope
By product: implantable, external; by technology: single chamber, dual chamber, biventricular/CRT-P, leadless; by application: bradycardia, conduction disorders, heart failure; by end user and geography.
Regional & Country Outlook
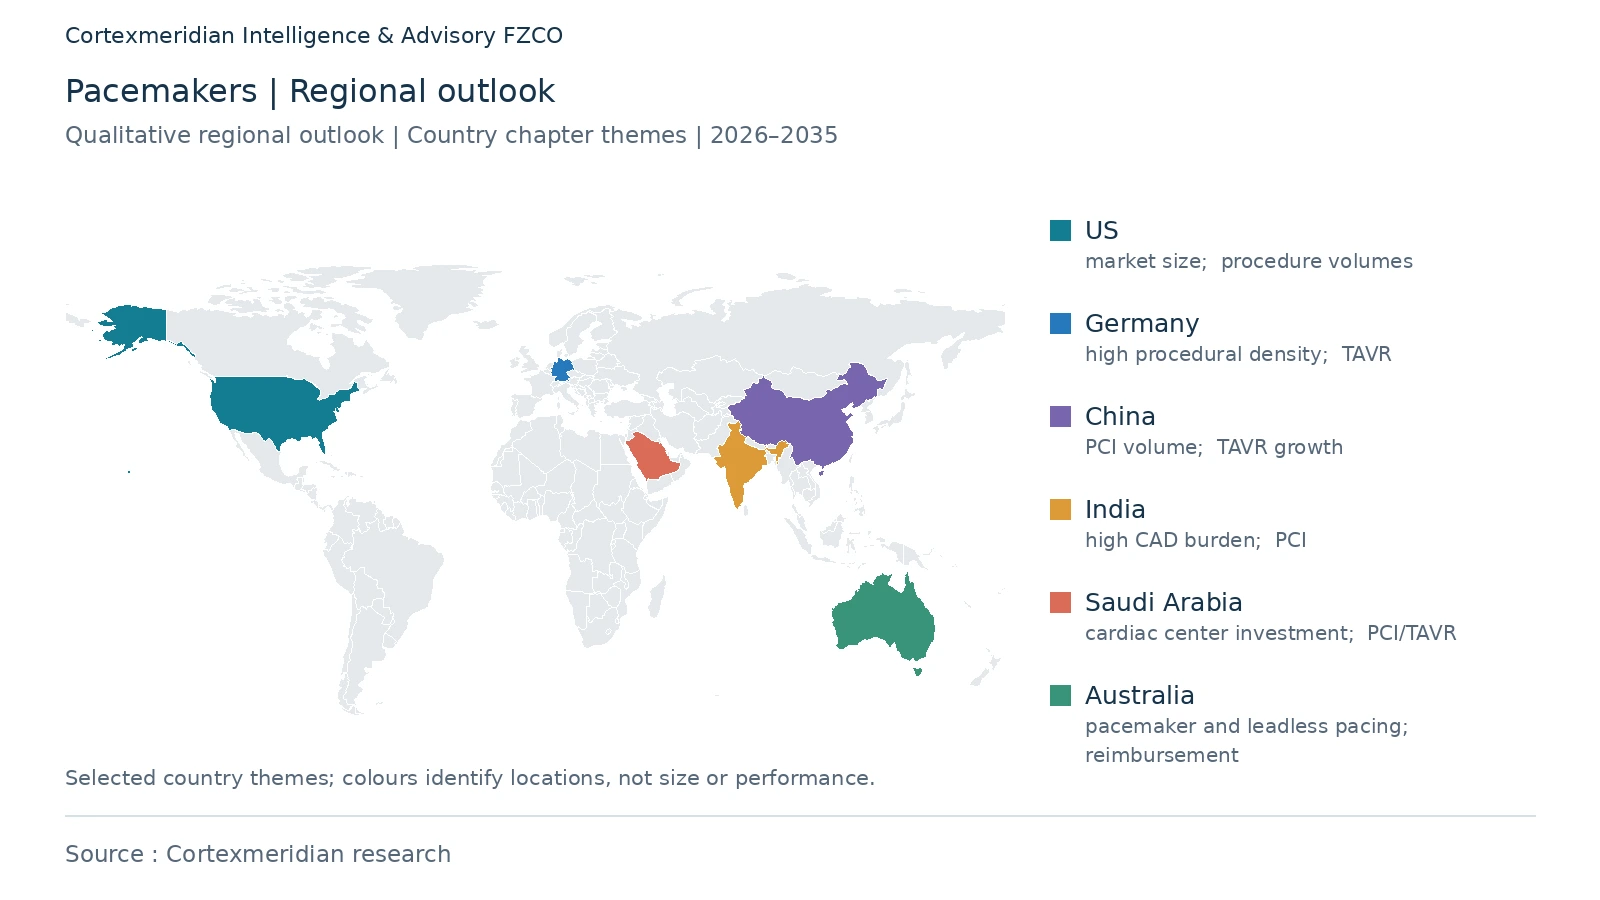
COUNTRY CHAPTER COVERAGE 1. US: market size; procedure volumes; pacemaker and leadless pacing penetration; FDA pipeline; reimbursement; Abbott/Medtronic/Edwards/Boston Scientific competition. 2. Canada: procedure volumes; structural heart; CRM; provincial reimbursement; hospital procurement. 3. UK: NHS cardiology capacity; PCI/TAVR; rhythm management; waiting lists; procurement; reimbursement. 4. Germany: high procedural density; TAVR; EP/CRM; reimbursement; hospital adoption; supplier competition. 5. France: structural heart; interventional cardiology; reimbursement; hospital volumes; device adoption. 6. Italy: pacemaker/CRM demand; regional hospital capacity; reimbursement; procurement. 7. Spain: cardiac procedure volumes; pacemaker implantation; public hospital procurement; reimbursement. 8. Netherlands: advanced structural-heart and EP adoption; high-value devices; digital monitoring. 9. Switzerland: premium cardiovascular technologies; private/public hospital mix; structural heart; CRM. 10. China: PCI volume; TAVR growth; local device companies; volume-based procurement; pricing; regulatory approvals. 11. India: high CAD burden; PCI; TAVR growth; price caps; domestic manufacturing; hospital expansion. 12. Japan: aging population; TAVR/CRM; reimbursement; domestic and multinational competition. 13. South Korea: advanced cardiac intervention; TAVR/EP; reimbursement; hospital technology adoption. 14. Australia: pacemaker and leadless pacing; reimbursement; cardiac centers; remote monitoring. 15. Brazil: PCI and rhythm management; public/private access; import pricing; hospital concentration. 16. Argentina: cardiology procedures; import dependency; pricing; reimbursement; private hospitals. 17. Saudi Arabia: cardiac center investment; PCI/TAVR; Vision 2030; tenders; localization. 18. UAE: premium cardiology services; structural heart; private hospitals; technology adoption. 19. South Africa: public/private cardiology split; PCI/CRM access; reimbursement; distribution.
Competitive Landscape & Companies Covered
Medtronic; Abbott; Boston Scientific; BIOTRONIK; MicroPort CRM; Medico; Lepu Medical
Pricing & Ecosystem
Pricing, Cost & Revenue Intelligence
Pricing intelligence benchmarks capital-system ASPs, disposable/consumable pricing, procedure-linked device pricing, service contracts, software subscriptions and regional tender dynamics where applicable. The model distinguishes capital equipment from recurring revenue and evaluates discounting, bundling, distributor margins, reimbursement sensitivity and premium technology price realization.
Value Chain & Ecosystem Analysis
The ecosystem maps component and sensor suppliers, materials vendors, device OEMs, software/AI partners, contract manufacturers, sterilization and packaging providers, distributors, hospitals/diagnostic laboratories/ASCs, clinicians, payers and regulators. The analysis identifies control points in the value chain, recurring-revenue pools, channel dependencies and partnership opportunities.
Opportunity & White-Space Analysis
A weighted opportunity model scores product segments, technologies, countries, end users and accounts using growth, market size, clinical adoption, reimbursement, competitive intensity, regulatory accessibility and margin potential. Priority white spaces include Leadless pacemakers, MRI-compatible systems, remote follow-up, battery-life innovation and emerging-market penetration.
Executive Summary
Cortex Meridian Research estimates the Pacemakers market at USD 5.8 billion in 2025, rising to approximately USD 10.0 billion by 2035 at a CAGR of 5.7%. Conventional pacing is already mature, so growth is increasingly driven by premium leadless technology rather than by unit expansion alone.
Abbott’s AVEIR DR broadens leadless pacing into dual-chamber therapy, while Medtronic’s Micra platform maintains strong competitive pressure. If clinical evidence and reimbursement continue to support wider adoption, leadless systems can materially increase average selling prices and expand the eligible patient population, making mix shift the central driver of market growth.
Key Takeaways
- 2025 Cortex normalized estimate: USD 5.8 billion
- 2035 normalized outlook: USD 10.0 billion
- Normalized 2025–2035 CAGR: 5.7%
- Key growth drivers: Aging population, arrhythmia prevalence, rising implant volumes, longer device life and improved leadless technology.
- Priority opportunity areas: Leadless pacemakers, MRI-compatible systems, remote follow-up, battery-life innovation and emerging-market penetration.
- Primary competitive set: Medtronic; Abbott; Boston Scientific; BIOTRONIK; MicroPort CRM; Medico; Lepu Medical
Table of Contents
List of Tables
- Global market value, 2021–2035
- Market by product/device type
- Market by technology
- Market by application/procedure
- Market by end user
- Market by region
- Country market sizing
- Installed base/procedure/test indicators
- ASP/pricing benchmark
- Company/product benchmark
- Opportunity attractiveness scoring
List of Figures
- Market size and CAGR outlook
- Segment attractiveness matrix
- Technology adoption curve
- Regional opportunity heat map
- Competitive positioning matrix
- Value-chain ecosystem map
- Pricing/revenue model
- Opportunity prioritization matrix
Research Methodology
Methodology
Cortex Meridian Research applies a triangulated market-sizing framework combining company disclosures, regulatory databases, procedure/test volumes, installed-base indicators, shipment and utilization data, hospital and laboratory purchasing patterns, reimbursement signals, product approvals, and primary research. Public market benchmarks are used only as external calibration points; Cortex values are normalized to the defined scope and forecast period. Forecasts consider technology adoption, procedure/test growth, replacement cycles, pricing, reimbursement, regulatory changes, and regional healthcare investment.
Data Sources & Validation
Company annual reports and investor materials; FDA, EMA and other regulatory databases; WHO and national health agencies; peer-reviewed clinical literature; procurement and reimbursement sources; hospital/laboratory statistics; trade and shipment indicators; company product portfolios; primary interviews; and public market benchmarks used for calibration.
FAQ — Buyer Questions
Q: What is the 2025 global Pacemakers market size? A: Cortex Meridian Research estimates it at approximately USD 5.8 billion.
Q: What is the 2035 market outlook? A: The normalized outlook is approximately USD 10.0 billion, based on a 5.7% CAGR assumption.
Q: What are the major growth drivers? A: Aging population, arrhythmia prevalence, rising implant volumes, longer device life and improved leadless technology.
Q: Which opportunities should suppliers prioritize? A: Leadless pacemakers, MRI-compatible systems, remote follow-up, battery-life innovation and emerging-market penetration.
Customization Options
Customization can include country-level sizing, procedure/test volumes, installed base, ASP benchmarking, hospital/lab account mapping, competitor benchmarking, product pipeline analysis, regulatory and reimbursement tracking, KOL mapping, distributor/channel assessment, and opportunity prioritization.
Need something this report does not cover?
Describe the decision you are facing. If a published study already answers it we will point you there; if not, we will scope the work and come back with timeline and cost.
CM-MD-0006 · CM-MD-P1-1006 · 180-220 pages · Published October 2026 · Cortex Meridian Medical Devices Analyst Team